Showing posts with label Real Estate. Show all posts

Saturday, August 19, 2017

Currency Cloud; Doubling-Down on a Fractured Inflationary Policy

Do you really hold title on property that's stored on the cloud? I don't know about you, but I don't trust the cloud. There is something that makes me think twice about the idea of owning something that I can't store myself. Yes, I know that cloud purveyors of goods promise that we really 'do' own whatever it is that they're selling us. Yet, whether I buy music or software, I want to hold it in my possession; even at the risk of making a mistake and losing it due to a hard disk crash or something else.
Since humans begun to trade, holding title over property was essential, no matter how informal that title was. This is why, the medieval system was destined to fail. Only kings could own productive property such as land and other important resources. Let's also remember that in the communist system the concept of property title over any productive asset is eliminated. We all know where all communist systems went.
So what would you say if I told you that we are now briskly moving towards a cloud-based monetary system. The International Monetary Fund, the only central bank type in the world with a clean balance sheet, created the SDR's as a direct replacement for all world currencies; especially the dollar. An SDR is a Special Drawing Right, a debt instrument no different than the US dollar, issued by the International Monetary Fund.
Central banks around the world understood in 2008 that our present inflation-based monetary system based on the dollar as an exchange currency died the moment that real estate problems in the US affected the whole world. The patient almost died. As a result, all sorts of untested monetary drugs were created. These drugs were given to the patient in overdose fashion. Every major central bank around the world loaded its balance sheet with anything they could: government bonds, real estate, corporate debt and stock. But to understand why, we have to look back.
At the end of the 1990s, the main financial institutions in the world got together to rescue Long Term Capital Management, one of their own. This hedge fund managed by Nobel laureates faced collapse and damage to the financial system as their mathematical models drove them to overinvest in a defaulting Russia. This was a case where banks bailed banks out.
But in 2008, it was these banks that needed a bigger balance sheet to rescue them. This is where central banks entered the picture.
So what now that all the central banks around the world have destroyed their balance sheets? What will happen in the next recession? Who's going to rescue the central banks? The only institution with a clean balance sheet left his International Monetary Fund. To understand inflationary monetary fund one must understand Ponzi schemes. Both require larger players to enter the game. Yet, both will fail eventually. The catastrophic outcome increases in size as the Ponzi scheme gets bigger.
However, changing the monetary system is more than just changing one paper money for another. In the past, we went from gold or silver to paper, for example. This time, central bankers want to change the way property title works when dealing with money. They want to eliminate the cash-based society altogether.
At first sight, one could think that because of our extensive use of credit cards, we already have a cashless system. But this is not what central bankers think about when looking at cash.
Recently, interest rates when negative in several European countries. In essence, the lender pays the borrower a premium in exchange for the borrower placing the lender's money at risk of loss. Throughout history, if the borrower put the lenders money at risk, it is the borrower who had to pay the premium.
If assets like money or labor are free, how many should you get? All that you can, of course. So if money or labor pay you for taking advantage of them, how many should you get? I guess the only answer is: infinite. This is the absurd result from letting academics control our lives. To them, it's just a simple mathematical formula.
So how did citizens respond to negative interest rates punishing their savings? Instead of infinite spending or infinite lending they took the money out of the banks and held it in cash. This is because no matter where interest rates are, positive or negative, cash is a zero interest debt instrument. Consequently, central bankers went crazy. Their beautiful formulas didn't work. So what to do next? Perhaps rethink the formulas? No! Let's eliminate the stinky cash. Let's make all money virtual. In that way, no one can take money out of their interest rates system. Let's say that again. In a cashless society, there is no place to hide from central bankers.
Stock and commodities traders everywhere know that, when markets are extremely volatile, staying in cash is a very viable riskless alternative. Well, so much for that. No one will ever be able to do that again; or at least until we realize central bankers are not looking after our best interest.
But like everything else, a cashless society will also place every citizen within closer reach of government and those who influence it most. A real scary thought.
The IMF made China responsible for the launch of the SDR. In August of 2016 China issued the first debt instruments within the SDR system. Visit www.acchain.org for more information about their progress. Their immediate goal is to securitize assets with these SDR's. Think about it. Securitizing US real estate during the early 2000s wasn't enough for bankers around the world. By the time those so-called assets were passed through the derivatives machine, bankers were really happy. Yet, everyone lost all sense of where real value lied. When the real estate bubble blew up, many were unsure of who owned the asset in the end. Many foreclosed properties stayed in limbo as it wasn't clear who in a series of titleholders was the final owner of the debt. It was akin to a musical chairs game where multiple people ended over a single chair.
https://www.acchain.org/en/ret_operation.html
The first SDR's in China where backed by tea leafs. One way to understand this is to simply look at commodity futures; contracts of things like cattle and coffee. Yes again, futures are derivatives that allow for extensive speculatory trading. Counting all gold future contracts being traded at any one time will prove that most of them are being traded for speculation and will never be turned in for commodity delivery. There are a lot more contracts that goods available. Moreover, while Goldman Sachs has every intention of making money from gold price fluctuations, they have no interest in receiving truckloads of bullion at contract expiration. As such, SDR create a natural shortcut for speculation.
The first real estate residential community in Dallas, Texas is been securitized with SDR's. Due to US regulations, no Americans can participate in such SDR's. Well, I'm sure Goldman Sachs has a way of going around the rules. But I sure can't participate.
It does sound fantastic to think that our next global currency will be based with real assets. But who said citizens would barter with SDR's?
Enter crypto currencies. The recent craze for Bitcoin and all the other copycaters represents the best early Christmas gift central bankers never asked for. They fell in love as soon as they got their hands on it. Let me explain.
One of the problems central bankers have is how to convince citizens to switch from physical currency to cloud-based currency. Fortunately for them, the market has created a solution to their dilemma. Central bankers don't have to convince anyone. People are tripping over themselves as they bid up the price of crypto currencies in fear to be left out.
I know that the promise of crypto currencies is one of a system that lies outside of government watch and control. But the IMF and central bankers are not keeping the secret; they have publicly announced their love for crypto currencies. Have you noticed the recent headlines that Goldman Sachs is recommending its customers to buy Bitcoin? Coincidence? Give me a break. After seeing the depth of corruption in our US system, I'm even in doubt of what real mom is. From Google, to Facebook, to Goldman Sachs, to Bank of America, to my local electoral polling system, I don't trust any of them. Here in Broward County, just south of where I live, there are 40% more registered voters than citizens. Broward county was won, hands down, by the Democrats. We even have 140-year-old voters who seem to love the Democrats.
Bank of America Refuses Cash
For Mortgage Payment
And if that's not enough cheating, asking to get more than $1,000 in cash from my Bank of America account could get me arrested. It seems that the bank's liabilities are now backed by my money in their possession. Understand this: If they fail, government won't have to bail them out. I am going to bail them out without being asked. It's all part of the new contracts every US citizen unknowingly signed.
So, are you still excited about having a cloud-based society? Ponder the question of who, in the end, holds title over your property and money? Now that crypto currencies have been incorporated into the IMF's SDR plan and after experiencing what it is to hold title over a cloud-based asset, you see how this begins to seem much more like a medieval system where the powerful reside within the castle and the rest of us toil the rented land while being the first exposed to elements and foreign attacks?
I don't know about you, but nothing about this Ponzi scheme bubble makes me like it at all. Central bankers and the IMF will promise SDR's as the next stage in a healthy and vibrant economy. I just don't buy it. We are simply gaining speed right before impacting the wall.

Article on LinkedIn

Wednesday, February 19, 2014

US Builders; Anything But Confident

Like when discovering that Santa doesn't really bring toys to children around the world, economists everywhere fell off their chairs after receiving Builder Confidence Data this morning.
illustration of a small home
Negative NAHB Builder Sentiment
Today, the National Association of Home Builders' Housing Market Index shocked the world of academia by revealing a negative confidence level among US builders. Considering that any number below 50 is bad news, last month's 56 was pretty OK; especially now that we convinced ourselves that mediocrity is the new recovery normal. Experts anticipated a number between 54 and 58. Now imagine their surprise when the news of an silly 46 hit the wire.
Naturally, the immediate reaction was to blame the weather. And why not? Everybody is blaming the weather.
aerial photo of the hoover dam
US builders aren't sissies
But if I know something about builder greed is that it is stronger than the weather. Think of all the great construction feats that took place in this country over the last couple of centuries. From trains to bridges, builders are anything but sissies.
Does this mean that something else may be at fault? Well, how about Greed's balancing partner: Fear?
Back on May of last year, I covered the real estate market in an article called Robust Real Estate Hides Truth. There, I described the fundamental issues challenging the industry. But lets bring everybody up to date on those issues.
Last year, homes were being sold too cheaply for builders to want to compete. This is because, after inflation, it was more expensive to build a house than to buy one built ten years ago. This is especially true when investors where the main market buyers. Remember that investors buy wholesale. The retail consumer had no chance to compete because homes were being appraised about 15% below the asking price while bids were being made 10% above ask. This meant that only buyers with a 20% to 30% of extra cash at hand could play the bidding game.
logo in black background of FHA logo with "Your door to homeownership" legend
FHA buyers were out of luck last year
Then consider the fact that this was an environment where the banking system failed to fully come back as a source of real estate loans. Even today, builders are complaining about the difficulty to get their projects funded. Just think of little home buyers. Now completely forget about FHA buyers. Low appraisals take most of them totally out of the market. I am sure that you heard stories about people spending up to a year trying to buy a house. These poor souls were being outbid by pro's.
Most homes were being sold to investment managers like BlackRock, rather than families. The interesting part is that this was no secret. Recently, BlackRock unveiled bonds made up from billions of dollars of securitized trounces of homes bought specifically to be rented. It should be clear that any home price increases were due to the vicious fight for inventory being waged between various investment managers.
Now put yourself in the shoes of builders. Imagine a market where capital is either too expensive or impossible to get. Add the fact that market prices for the goods you make are much lower than your cost to manufacture them. Then, consider that your main customer has yet to find reliable loan sources. Finally, think of the fact that the next generation of potential home buyers prefers to live at home with their parents.
All things being considered, there is simply no reason why builders should be upbeat.
Thankfully, they have enough sense as to not blame the weather. But the same can't be said about economists who insist that the weather is behind the malaise we are now seeing across the economy. From government to academia, naive optimism about a recovering real estate market abounded despite the evidence.
photo of three large snow plowers clearing a highway after heavy snow
Don't blame the weather
In Robust Real Estate Hides Truth I described how the so called recovery lacked fundamental strength. The fact that a part-timer like myself can analyse the same data as the pro's and come to diverging conclusions isn't surprising. What's incredible is when the pro's see their models crashing back to earth after such a short time.
This is why I have a hard time thinking of economics as a science. Pseudo-scientists like economists are great at curve-fitting until they see what they want from charts. Real scientists would be glad to be surprised by the evidence rather than by the failure of their fully developed models.
Illustration of "Fear to Greed" gauge showing that fear is stronger
Fear is stronger in this market
In a nutshell, this morning's news should have surprised no one. The home market is out of inventory and those who make the widgets have no incentive to make any more. These are the distortions typical when ineptitude is rampant among those who control the economic levers. So far, housing and employment have demonstrated the degree of market distortion and dysfunction that is our present reality. This despite a clueless president who continues to brag about his brand of recovery.
For now, keep walking people. There are no new news here!


2014/02/19 9:06 AM Update
Housing Starts and New Housing Permits data collapse in January. 
From an expected 975,000 in New Housing Permits, the final number came in at a meager 937,000 for a 5.4% in month-to-month decline. 
New Home Starts did worse. From the anticipated 950,000, the real number dropped by 16% when compared to last month to 880,000.
Despite the now normal tendency to blame the weather, the West may tell a different story. The West fell by 26% in a Permits month-over-month comparison and by 17.4% in month-to-month New Home Starts. The West is the second largest component in the survey and was not affected by the weather. 
Whether this is a fluke or a fundamental indicator of a weak economy, time will tell. To me, this has an eerie resemblance to April, 2006. Despite clear fundamental flaws, the data had just begun to show housing weakness. Back then, it took two years for everyone to finally admit we had a problem. 
In 2006, the problem was irrational exuberance; too much of a good time. Today, the issue is incompetent malaise driven by a White House leadership that insists in maltreating capital and business; thus creating a level of uncertainty that can't be lifted by all the money pumping at the Fed and through the Japanese carry-trade industry.

Tuesday, June 25, 2013

Siegel, Clearly Simple Wealth Approach

Tall Feng Shui style photo of dark rounded rock over white backgroundKeep it Simple, Stupid  isn't the same as Keep it Stupid Simple. Both are KISS principles; yet they send different messages.
The former implies being less than brilliant, to say the least. This is the message that most intellectuals deliver to their audience. Their discourses often create a sense of awe for their genius while leaving a gaping understanding-void behind. They seem to thrive from dishing unbreakable magic.
On the other hand, the latter KISS, which is less common but the more adequate alternative, accentuates the need for simplicity. This is what Professor Jeremy Siegel does while also being master of the stock universe at prestigious Wharton School of Business. The confident, succinct, transparent, charismatic and perpetually optimistic professor has written a book that just leaves you feeling good, despite all the noise and fear roaming the nation right now. The Future for Investors demystifies the drivers for success behind the work of great money makers like Oracle of Omaha, Warren Buffett. No señor, not even a doctorate degree from no less than MIT gets in the way of professor Siegel's ability to clearly explain to average people.
Evidently, to think in terms of either growth or value investing is wrong. Based on Siegel's extensive research, one should evaluate market expectations through the lens of market pricing. Is the market expecting high asset value growth and has therefore pushed asset prices higher? A yes, suggests looking elsewhere.
Composition photo of financial markets giant Jeremy Siegel next to his new book "The Future for Investors"
The Future for Investors at Amazon
Next, scavenge among assets with lower growth expectation for those with solid cash flows. Any asset with high capital investment requirements should be put to the side until cash is no longer being siphoned. Previous studies have debunked the myth that higher capital investing is essential to lead the industry. This also puts tremendous pressure on the idea that gold, a non cash-flowing asset, could deliver more than mere parity with inflation.
Something I found very interesting within the subject of cash flows is the suggestion that the investor and no one else should determine how to re-deploy corporate profits or dividends. Letting management "invest" the money leads to poor results in the aggregate due to low capital investment returns. Then there is the fact that letting government decide how to invest is even worse. Government often spends several times more to create a job than the job pays. Handing cash would be a much more effective way to use money. But who wants to hand out cash without resulting in value add.
Photo of fifteen one hundred dollar bills arranged in ascending house-looking structures
Real Estate Investments
Only the reinvestment of cash flows through the purchase of additional shares leads to substantial market out-performance; especially during recessionary times. Now, this explains why Buffet acquired insurance and consumer staples businesses. These companies deliver great and sustainable cash flows that can be reinvested into more cash flowing assets. And I thought that staying away from fast growing businesses was a cute way for a conservative old man like Buffet to invest. He has really misrepresented his approach. The goal is not to seek businesses that a simple Cornhusker could understand. No, the goal is to buy as much cash flow as possible with every penny so that more cash flows could be acquired next. The math behind the compounding properties of this method is very robust. To think that Mr. Buffet would support higher taxes, a way for citizens to invest in the country, while he clearly lets no one decide how to invest his dividends makes me feel betrayed by the Oracle. Sadly, this feeling has now surfaced twice. I previously wrote once about it in my Secret double-life - Warren Buffet spices things up with leverage post.
That's it. Low expectations and high reinvestable cash flows. As the Geico commercial would read, "So easy a caveman can do it".
Professor Siegel also proposed a great thesis for how the negative impact from the upcoming demography shift will be counterbalanced by global growth. Soon Baby-boomers will start selling their accumulated assets to pay for retirement. Siegel feels that the massive wealth and consumption expansion taking place across the developing world will help sustain present asset prices. But I am not so sure about it.
Photo image of modern Chinese metropolis in full bloom
There are three factors that in my mind could impede his scenario from taking place. Deficiency, timing and risk profile could make his calculations unrealistic. First, all markets are deficient. Whether there is a 10% or a 90% deficiency in the transfer function needed to match boomer assets for sale with growing demand elsewhere is presently unknown. Have you ever needed to sell something yet failed fining the buyer who would pay your price? Yes, it happens all of the time. After you sell at less than you wished, you will inevitably find someone who would had paid more. Why was it so difficult to find the buyer when you needed it? Because all markets have a deficiency factor which could range from very low to very high. We don't know how efficient each relevant market will be over the next 30 years. What we know is that even a highly efficient market will offer enough friction to call for a review of the math used.
Second, timing means that citizens in developing economies could be willing to buy Boomer assets years after the sale took place. That would be disastrous for sellers even when buyers largely outnumber them.
Third and presently evident is risk profile. Equity prices have resiliently gone up because of market distortions created by the Fed. Risk-adverse buyers are having to shorten their time horizon to compensate for the higher risk associated with the assets they are now buying; assets like dividend paying stocks and residential properties for rent. Any change in economic risk will probably force assets out of their uncommitted hands.
Photo of two Baby Boomers over a Volkswagen van in the 60's
Boomers
I am not sure that developing consumers will be ready to buy the same type of risk assets as Boomers did. Boomers grew up in a very different economic environment. Their parents experienced great wealth growth; which gave them the opportunity to party la Vida Loca while question every rule and standard. Boomers display a sense of invincibility and entitlement missing from any other large group. Instead, developing nation citizens would surely behave like members of the Greatest Generation, those that fought in WWII and built the industrial nation that we now know. Global growth citizens will probably be financially conservative and hard working. So, I doubt that they will have the same risk appetite than Boomers. If their savings are redeployed by money managers into riskier asset classes, then we risk discouraging these savers while also creating great market volatility and rampant crashes; a scenario that is probably closer to the truth. I would love to see if professor Siegel has accounted for the three concerns I am raising here.
Professor Siegel's book is fantastic. His delivery is as welcomed through his writing as when he talks to the CNBC cameras. Thank you professor for your hard work and commitment to a better future for investors.

Book Title: The Future for Investors
Book Subtitle: Why the Tried and the True Triumph Over the Bold and the New
Author: Jeremy J. Siegel
Publisher: Crown Publishing Group
ISBN: 140008198X

Monday, June 24, 2013

Great-Depression Expert Abdicates, We'll Miss Ben

From the time when he announced he would miss Jackson Hall this year to the obvious resignation that pours over the cameras as he talks about the state of the economy, it is clear that Mr. Ben Bernanke is exhausted. Eight days ago, his boss fired him in front of a national TV audience. Rather than improving, important aspects of the economy like real cost of capital for small businesses and the system's velocity of money worsened even after the recession had ended in 2009.
Black and white photo image of Federal Reserve Chairman Ben Bernanke during a hearing
Let's wear Bernanke's shoes for a moment. It must be truly devastating to see that everything that you studied and learned from the Great Depression, everything that you prepared to prevent another one from happening, can't help you once you find yourself in the middle of it. Surely, he devised the economic maneuvers that would spark the comeback. He must have rehearsed each and every step needed for solving the biggest of economic challenges. More importantly, he must have trusted that historical evidence would motivate those in power not to repeat the same mistakes. But it was not to be.
In the words of Mark Twain, "history does not repeat itself, but it does rhyme". No matter what the US Federal Reserve may do, feelings of mercantilism and resentment towards those behind the financial markets resurfaced among citizens; just as they did when the nation faced the same foe close to 80 years ago. These tendencies have created once again an environment where people elected a politician who resonates with such poor market ideas.
To think that things would be different this time is like hoping that the next generation of teenagers will not drive mom's SUV over the speed limit just because there is plenty of evidence that it is neither necessary nor good. Teenagers learn by crashing. Perhaps we prefer learning through pain as well.
Whether you like Bernanke’s actions or not, he has been the only game in town; the only one really acting to solve the malaise. Apparently, he was also the only one who combined an understanding of the problem with the integrity needed to execute. Others knew what to do but remained quiet. Most had no clue about economics but yelled their opinion all the same.
Bernanke understood that markets are emotional and tried to deliver positive messages. Even when he knew that the window of opportunity would be narrow, he delivered enough liquidity to make markets forget the bad times for at least a moment. He knew that a liquidity trap would prove his approach right despite the many warnings of inflation by armies of detractors. He also had the backbone to stand up for what he believed despite seeing that both political sides were taking shots at him any time they had a chance. From my perspective, Mr. Bernanke is an honorable man who has served us with everything he could deliver.
Official White House photo of smiling and confident President Barack Obama
No Real Focus on Economy
But he could not do it alone. How else could Bernanke build valuable market confidence when the leader of the nation aimed his artillery to those holding the purse strings? Mr. Obama ignored the fact that fear mongering and business witch-hunts do nothing for investment confidence. The President has completely ignored dozens of lessons from history that have proven his brand of socialism ineffective. Obama over estimated his Jedi power over markets (if there is such a thing). But perhaps the most troublesome, our leader ignored the fact that Americans are creative enough when motivated to deliver solutions to any problem; whether economic or environmental. This was once a nation where corruption and filth were rampant a few decades ago. Yet, its citizens created models that the rest of the world now tries to emulate. Eat at a McDonald's restaurant in China to see what fighting a mob for a piece of burger feels like. In an instant you will be thankful of the order that we witness everywhere in this nation; order which wasn't always there.
For many poor leaders, fear and insecurities among subjects are essential tools for power preservation. Instead of motivating the nation, Obama has talked down to us as if we were all idiot children who must be made to comply. For a picture, think of the many psychologically abusive parents out there who really love their children and just transpose the characters. You are the abused child.
Notice that I say nothing about Congress. Decisions by committee don't work in business and surely fail in government just as well. Besides, I think that a leader is responsible for leading; so no excuses Mr. President. It is your job, even if no one can suggest a better way.
The President could have inspired hard work. Instead, he exploited feelings of entitlement among the masses. Instead of pushing for cutting unproductive spending in the same way that any CEO would do, he bickered over forced cuts from the Sequester. Complaining is the tool of the weak, I feel.
But rather than helping Bernanke's efforts, Obama took advantage of the resulting low National Debt Interest costs; thus ignoring the massive potential future risk to be faced by tax payers. Paying five to ten times more to rescue a job than what the employee gets in income is wasteful no matter how cheap money is right now.
Not long ago, we paid the same in interests for a much lower foreign debt. This is because Ben's liquidity push has made government borrowing costs lower today than any recent time. But interests will not remain low indefinitely and are thus headwind-risk for the Fed's actions. In other words, instead of lubricating, Obama created drag.
Photo of paper illustration with "Integrity is the willingness to live by our beliefs & standards" legend
Integrity
Washington is simply full of people focused on everything but getting the job done; from the President to the lobbyists, we are not being served well. Thankfully there was a Lone Ranger in the crowd.
I did not agree with everything Bernanke did. I nonetheless admire his stature and integrity. As the brilliant and confident person he is, I am sure that he doesn't need everyone to agree with him and that he values the insight resulting from intellectual debate.
With Bernanke leaving, no doubt we will get another bright person to take the controls at the Fed. What I am not sure we will get is another giant with the same degree of integrity and conviction. The next one may be a "yes" person who is willing to bend rules so long as the boss makes the request. Backbone is what I know we will miss most.
Thank you Mr. Bernanke. You are a great man.

Sunday, June 16, 2013

Stocks and Bonds: Where Cash is King

I probably made a fool out of myself on May 22 when I suggested that stocks were probably topping. In any case, I will not know how wrong I was until much later. For now, it is time for an update on what I am seeing in the markets.
Graph showing high volatility of price of S&P 500 futures from June 11 to June 13 2013
S&P Futures
Since my post, things have turned a little scary. The S&P is sitting at about a 3% loss after recovering from losses as big as 6%. Incredible swings are literally shaking money managers out of their convictions. Everybody who says that things are fine is having to think twice. The price chart to the right shows the trading activity on Wednesday the 12th and Thursday the 13th of August when viewed through the S&P Futures window. Yes, despite happening at the end of an already sharp drop, the curve depicts a wild roller coaster between the two days.
It is believed that the large Thursday's rise was strongly supported by the fact that there were many traders closing short positions to collect their profits. To close short positions, which are designed to make money when assets go down, traders need to buy the asset; adding to the upward pressure from others who felt that prices dropped far enough to make them cheap to buy again.
There is also the fact that the Federal Reserve has an announcement scheduled for next week. From reading my post, you would already know that stocks topped during Federal Reserve Chairman Ben Bernanke's testimony to congress. So, everybody will be paying attention to his words attempting to anticipate how much will the Fed continue to distort markets through their monetary intervention.
Composition image of ascending asset prices. There are two people illustrated. One seems horrified during price correcting crashes. The other seems ecstatic as during peaking bubbles.
Boom and Bust Cycle's Reversion to the Mean
Finally, next week will be quadruple expiration week. Also known as Quadruple Witching, options and futures will expire forcing many funds to re-valance their portfolios. This means that there will be a drop in price volatility, which will surely be welcomed by those still shocked by the gyrations of the last two weeks. The insurance needed for portfolio protection comes down in cost during this period. There will also be a natural push higher on asset prices due to portfolio re-balancing; also a welcomed fact.
After the recent drop in prices, the Efficient Markets Theory would suggest that the risk is to the upside. Recall that no market moves in a straight line. All markets tend to push high further than they should, resulting in bubbles. Markets then correct lower than equilibrium, creating crashes. So for now, there is the chance that markets have temporarily pushed too far to the downside.
In general, there are plenty of factors which will probably push market prices higher in the near term. This means that those who feel that the economic strength is not what it seems will take any price increase as an opportunity to raise cash.
While equity and bonds markets do not directly impact our "real" economy, our "real' economy impacts these markets as well as our businesses and our lives in general. To me, asset markets are therefore great indicators of what is happening to the real economy, if not the creator of such changes.
We are now in an economy where the white house is on an business witch-hunt, bonds are vulnerable, housing is sitting on poor foundations, equities are valued by jittery capital and where there is no fundamental full-time employment growth or long term capital investment. Whenever the market decides to price these factors, asset prices will go down, perhaps by quite a bit, thus making cash the king of the market.

Saturday, June 15, 2013

You - Creator of All Financial Bubbles

You are the reason why we have bubbles. Stop blaming others and face the reality. Don't believe me? Answer this question: if you knew that a company will go bankrupt soon, how much would you pay for its stock?
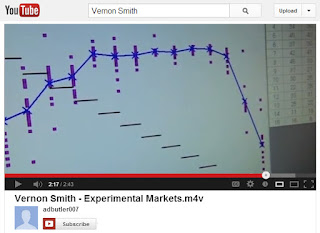
Screenshot image of YouTube's web page where the documentary describing some of Vernon Smith's experimental economics work is hosted.
Launch Bubble Experiment Video
Based on the studies that earned Vernon Smith his Nobel Price in economics, if you are human, you would be a creator of bubble. You would drive the price of an asset that will soon become worthless to a unsustainable level until it inevitably collapses.
Since the eighties, Mr. Smith has been conducting experiments that reliably created nice and frothy financial bubbles no matter who was behind the buy button. It seems that when you ask people to make money, everybody has it within themselves to be able to turn into an unmentionable, like a Wall Street banker or worse. I suggest that you check the short video describing one of these tests. Seeing Mr. Smith's experiments has changed my views about bubbles. I am convinced that we will continue to create them.
Right now, a bubble in bonds is ready to pop any day. But since almost no one understands bonds, it will probably be misrepresented. Bonds are the kind of economics stuff that makes people's eyes glace.
What will surely get lots of airtime are the effects from the blow up. Whether we know it or not, bonds affect everything. Interest rates and borrowing are tied to the bond markets. Bonds also affect cash-flowing assets like real estate and dividend paying stocks.
Photo of white balloon on black background. The balloon has a line drawing image of an asset price graph showing a boom and bust cycle
Bond Bubble
In a previous post, I covered the current state of the housing market and the many distortions taking place. Benjamin Graham, the father of value investing, once said "in the short term, the stock market behaves like a voting machine, but in the long term it acts like a weighing machine". This phrase too applies to the real estate market. In the short run, the market is distorted. The Fed's push for liquidity plus a surplus of global savings create a tidal wave of funds seeking a place to land. As the Federal Reserve's Quantitative Easing program crowds these funds out of Treasury Bonds, the inevitable result is that way too much risk-adverse capital is being deployed by companies like Blackstone to drive prices of the wrong type of assets. Assets that would be much more stable when fueled by patient capital from home buyers instead. Even builders have noticed the distortion. Lumber prices are way down, as a sign that things are not peachy on the housing supply side.
Real estate does not have to be in a bubble for home prices to come down sharply. As long as bond values collapse, real estate will correct to the point of long term balance. Even Robert Shiller, the greatest authority in real estate and the creator of the S&P Case-Shiller Index, has been warning that a real estate bottom has not been reached yet. He is clearly skeptical of the sustainability of the present rise in the housing index that he created.
Just 13 years ago, we saw the collapse of the Tech Bubble. Then, in 2008, we all played the game once again. We witnessed the implosion of the financial derivatives and real estate bubbles. To prevent these bubbles from happening, many have called for more government oversight and more regulations. Yet existing regulations proved inadequate. Meanwhile, bigger regulators and the structural rigidity from extensive regulations do create a lethargic-bureaucracy where progress is slow and innovation is absent.
Photo composition of small boat floating over the ocean with a piano and stool falling off the sky. There is the legend: "Murphy's Law" "If it can go Wrong, it will !"
Theory of Constraints
That regulations do not solve the problems should be readily understood by those with a basic knowledge of Eliyahu Goldratt's Theory of Constraints. Knowing with certainty that Murphy's Law will occur does not give any indication of where it will happen. Likewise, knowing that bubbles will happen does not mean that we know where to place the right regulation. A bubble will simply pop elsewhere. This is a fundamental fact known by operations experts all around the world. As a business manager, if you are not abreast of the wealth of knowledge that now forms the core of practices like Six Sigma and LEAN, you are absolutely and without a doubt doing a disservice to your company, family and society. The Toyota Way, which is part of what created this fantastic operations movement, has instituted effective methods to successfully deal with constraints of varying nature, such as those addressed by Mr. Goldratt.
Logo image of Regulations.gov, the government's wiki site where they intend to gain help from the people on new regulations to create.
Regulations-happy Nation
Incredibly, our politicians and the public seem to be perpetually engaged in a fruitless merry-go-round as they hold hope that regulations can be effective. Inexperienced warehouse managers fall on the same traps. Thankfully, the answers are ready and available to those who take the time to invest in a little bit of knowledge. Simply put, no amount of regulations will prevent constraints (or bubbles) from happening.
In conclusion, the evidence suggests that, like Murphy's Law, bubbles will happen. Perhaps it is time for the bond bubble to pop next. But Rather than placing blame, we should admit that bubbles are within us all. There is good scientific proof supporting this belief. We should also understanding that regulations will fail to prevent bubbles because of difficulties anticipating where to place such regulations. On the other hand, and since bubbles are created by incentives, we should look at incentives as a way to prevent bubbles. Maybe there is a lesson within operational practices at places like Toyota after all.


Thursday, June 6, 2013

Price Increases - Targeting Just Past Nuisance

Upset your renters only to the point before they'd move.
This technique is what rental property owners view as the best way to increase the value of their assets. They use what's often referred to as the nuisance rental increase. Small increases in rental prices become a nuisance to renters but no more. As a result, occupancy remains the same while revenue increases substantially at the margin.
For businesses elsewhere, it is not as simple. Often, customers can walk away without having to bring in a U-haul. Price elasticity is much more difficult to anticipate. As a result, price increases risk damaging client relationships or even loss of share. Because sales teams are strong detractors of any corporate plan to increase selling prices, it is safe to assume that all companies struggle pushing inflation to their customers. 
Sepia photo image of a dike break due to floods.This is something that the Federal Reserve understands well. They take advantage of the fact that the market displays plenty of friction when trying to pass inflation from input to output. What this means is that businesses everywhere are the first to suffer when the economy experiences inflationary pressures. Because profits decrease one dollar for every dollar of cost increases, the associated damage to businesses is high. Yet, businesses still find it difficult to efficiently transfer inflation to their customers . 
The fact that raising prices is difficult makes it noteworthy when empirical evidence uncovers a wave of increases. Usually, businesses will hold until they can no longer sustain the pressure. Then, suddenly prices increase by quite a bit. This would be analogous to a dike break. 
I have observed costs at Costco increasing by a large percentage: in some cases over 10%. Costco is a great indicator of what the consumers will experience because they follow a strict policy of always marking all products exactly 10% above their cost. This means that any increases reflect actual cost changes at their vendors and not within Costco. So, price increases throughout the store result from price increases throughout their supplier network. As almost all important American consumer companies sell through Costco, their increases are quite responsive to market movements. Unlike Costco, most other companies retailing goods to consumers raise prices after a central decision at corporate, which masks market gyrations.
Photo image of the product isles inside of a Costco store.
Another sign of accelerating inflation comes from the transportation sector. Transportation affects the cost of all products. If you ever wonder how is it that there is a large difference between the cost of a coffee bean at the farmer and at the store, you probably get an idea of the costs of transportation contained within the products that you buy. Yes, Starbucks makes a good profit for themselves. Yet, transportation costs are a substantial part of the price of the final product.
I am aware that UPS, FedEx and pretty much all transportation companies charge an additional amount to cover fluctuations in fuel costs. Fuel surcharges were the response to fuel inflation and are directly driven by market changes. But these are not the cost increases I am referring to. Instead, I am addressing the actual transportation rates charged. While many companies pay a discounted version of the official rate, a 6% increase in this rate will still equate to a 6% increase in the discounted rate. So it is easy to see how much inflation customers are experiencing from simply looking at the notices from these shippers to their customers. 
Photo image of the many Procter & Gamble products sold at a typical supermarket in the US.
If only things like fuel went up, the important stuff, the Fed would simply hide it under the rug. They do it every month in the Core Inflation data they report. But when inflation finally becomes a businesses output across the broad market, no magic trick can hide it. I am seeing evidence of this exact thing happening. 
Am I being overzealous? Absolutely, I could be. Perhaps there is no need to start panicking yet. Just note that all discoveries are born from plain observation and that the increases I noticed were not trivial in magnitude; they certainly exceed the 3% long term inflation number.
These increases go past the nuisance level and should be considered. Paul Volcker, former Treasury Secretary, has highlighted that it is important to be aware of any changes in the inflationary environment because of the risks associated with high stimulus by central banks and the potential sudden break higher. The last thing that we need now is for businesses to face another round of profit erosion. Let's keep an eye on inflationary changes.

Friday, May 31, 2013

Robust Real Estate Hides Truth

cartoon image in color of a small house
How great would it be to have lots of extra cash now that houses sell for much less than during the bubble? This is certainly the wish of millions of people looking to buy a house but struggling to get a loan. And now, to complicate things further, there are no more homes for sale. Things are clearly not as simple as offer versus demand.
The Pending Home Sales Index produced by the National Association of Realtors has hovered at a recent low due to insufficient inventories of homes available for sale. The glut of homes left after the bursting of the housing bubble seems gone. The few homes left are now going up in price due to aggressive bidding. As a result, the well respected S&P/Case-Shiller Home Price Index recently reported robust increases of more than 10% in year over year home prices. The natural conclusion to all these is that historically low interest rates have created a housing bounce.  
image of graph of CME's Lumber futures showing a sharp decline in the commodity
Lumber Future - Chicago Merchantile Exchange
Unfortunately, things don't look so great just below the surface. Lumber prices, for example, have collapsed since reaching a top at the end of last year. Whenever the housing marked is healthy, lumber goes up in price. This drop is an indication that construction has not recovered. Why wouldn't builders rush to construct more homes after selling prices and demand increased while competing inventories dropped? They clearly know something that the rest of us don't.
Meanwhile, real estate agents are seeing peculiar patterns in the market. Today, it is safe to be the highest bidder for a house. Once the winning bid is selected, everybody knows that appraisers will value the property much lower than the bid, dictating the actual selling price. After finding themselves in the middle of the housing bubble mess, appraisers are no longer willing to help drive pricing higher. To their detractors, appraisers are responding by being overly conservative with their valuations. As a result, winning bidders can eliminate competing bids before renegotiating a lower price that more closely approximates what the bank will lend. The bidding process is therefore irrelevant now.
Now that sellers know how to play the game too. They prefer to take a second or third highest bid if it comes from a cash buyer. Aside from eliminating low appraisal risks, sellers also protect against last minute loan denials, which seem to happen often. This means that high bidding cash buyers have the leading edge in this environment. 
illustration of a small house atop a pile of US cash
Hard Money
But these aren't the typical local cash buyer. The residential industry has long had a core local buyer: an investor who bids low and pays with so called hard money. Bidding high works against this type of investor because hard money costs too much in interests. To be profitable, he needs to bid low. He must also flip the homes quickly. Any delays reselling a house cost too much in interests. Notice that homes sold are not coming back to the market for resale and that winning bids are going up and not down. These local investors are therefore complaining that they are losing the bids to the few homes available. So who is devouring the homes for sale?
A recent conversation with a Palm Beach real estate investor shed light on the issue. "BlackRock is buying everything" he said after I asked who was buying all the homes. "And they are bidding high", he continued. BlackRock is a leading global investment manager best known for managing a few billion dollars of the Chinese sovereign fund. 
Every Wall Street hedge fund and money manager has been looking at all possible ways to take advantage of the state of the home market. Even Warren Buffet made repeated comments about loading up on homes if he could find a way to manage them. His comments reflect the fact that serious problems arise from holding residential properties within a portfolio. The market is quite fragmented; there are homes in every city in the nation. Yet, each home is different. Just buying all those homes is a logistics nightmare. Then there are the challenges of handling maintenance and payment collection. These has kept really big money out of each local market; until now. Rather than talking, BalckRock and a few others are acting.  
On May 29, CNBC's Squawk Box anchor Andrew Ross Sorkin asked BlackRock's CEO, Larry Fink, about the state of the economy. Among other comments by Mr. Fink, he said "we can't find enough good investments"; implying that they hold more money than what they are comfortable deploying. 
But how is it possible that there's so much capital available for money managers to buy all the residential inventory but there isn't enough for families to borrow to buy a home?
The reality is that BlackRock is not alone. There are massive pools of capital struggling to find assets where to invest. With low interest rates on treasuries and a Fed that continues to be a large treasury buyer, risk-adverse capital is being crowed out of typical investment vehicles. These funds are pushing dividend-paying low-risk stocks higher, for example. They also have depleted residential inventories.
cartoon image of a red blowing bomb, labeled "RISK"
Considering such large and homogeneous market participants, it should pay to know the risks associated with their involvement. First, there is the possibility that a change in macro-economic risk may increase fund redemptions at these firms, forcing their managers to dump properties at low prices. The real estate market would relapse; pushing many home owners further underwater and adding many more to the list.
Next, there is the question of exit strategy. When will all money managers get out of their investments and what if all exit at the same time? This unknown is probably what's forcing builders to think twice before fully firing up their engines once again. A large and sudden increase of new listings from exiting money managers as they take aim at the next hottest asset class could ruin builders who are caught flat footed.  
Then, there is the uncertainty of the returns. Despite great expertise within companies like BlackRock, there is the possibility that successfully managing properties at this scale may not result in the risk-adjusted profits they expect. In money management, there is always a question about being invested in the categories that have the highest yields. At some point, real estate property management will certainly fall below other asset categories forcing them to liquidate faster than would have been the case for local investors. 
Finally, there is the risk of exhaustion. There is the possibility that all or most of low priced properties have already be taken. Money managers have pushed prices higher, reducing the potential profits from the rest of the properties still in inventory. At the same time, prices are yet to be high enough for builders to construct new homes at profitable levels; thus limiting builders ability to drive the next leg up of the real estate recovery. 
In a nutshell, the recovery that we see in the real estate market should be approached cautiously. Purchases by families are not driving the apparent improvement. Construction of new homes is not responding either. Furthermore, the properties sold could suddenly comeback to the market, making it collapse once again. Until we see families buy sufficient homes at prices high enough to help builders remain profitable, any signs of recovery could be just a mirage.